close

March 2026

Health

How the Gut-Brain Axis Shapes Mood and Cognition

For centuries, Western science treated the human brain as an isolated command center. Neurological health, emotional processing, and cognitive performance were believed to be dictated entirely by the central nervous system, largely insulated from the systemic activities of the lower torso. When an individual experienced anxiety, depression, or brain fog, the therapeutic interventions focused almost exclusively on brain chemistry.

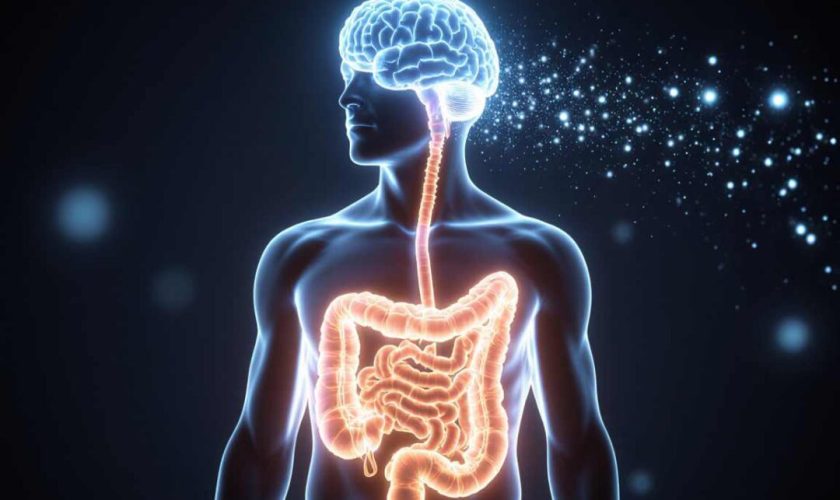
Modern medicine is undergoing a profound paradigm shift driven by the discovery of the gut-brain axis. This complex, bidirectional communication network links the central nervous system directly with the enteric nervous system, which governs the gastrointestinal tract. Far from being a simple digestive organ, the gut is home to trillions of microorganisms, collectively known as the gut microbiota, that actively synthesize neurotransmitters, modulate immune responses, and influence the structural integrity of the brain. Understanding this internal ecosystem alters our perception of mental health, proving that what occurs in the digestive tract directly shapes human mood, behavior, and cognitive longevity.

The Biological Architecture of the Communication Network

The gut-brain axis is not a metaphorical concept; it is a physical, highly complex highway system utilizing neurological, hormonal, and immunological pathways to transmit information throughout the human body.

The Vagus Nerve: The Neurological Superhighway

The primary physical conduit of the gut-brain axis is the vagus nerve, one of the longest and most important cranial nerves in the body. Running directly from the brainstem down to the abdomen, the vagus nerve acts as a real-time hardwired communication cable.

Crucially, roughly 80 percent of the nerve fibers within the vagus nerve are afferent, meaning they send signals upward from the gut to the brain, rather than downward from the brain to the gut. The enteric nervous system utilizes these fibers to upload information regarding gut inflammation, nutrient availability, and microbial activity straight into emotional and cognitive processing centers of the brain, including the amygdala and the hippocampus.

Neurotransmitter Production in the Enteric Nervous System

The gut is frequently referred to as the second brain because the enteric nervous system contains more neurons than the entire spinal cord. This independent neural network is capable of operating autonomously and produces a massive portion of the body’s signaling chemicals.

  • Serotonin: While serotonin is well-known for regulating mood, satiety, and sleep within the brain, approximately 90 to 95 percent of the body’s total serotonin is synthesized in the gut by specialized cells.

  • Gamma-Aminobutyric Acid: Essential gut bacteria strains break down dietary components to produce gamma-aminobutyric acid, an inhibitory neurotransmitter that dampens overexcitation in the central nervous system, mitigating feelings of acute anxiety and panic.

How the Microbiome Directs Mood and Emotional States

The composition of the gut microbiota—the specific balance of beneficial versus pathogenic bacteria living in the colon—exerts a profound influence over daily mood regulation and psychological resilience.

Systemic Inflammation and the Blood-Brain Barrier

When the delicate balance of the gut microbiome is disrupted, a state known as dysbiosis occurs. This imbalance often leads to an overgrowth of harmful bacteria that produce toxic byproducts called lipopolysaccharides.

An excess of these toxins causes the cellular lining of the intestinal wall to degrade, creating microscopic gaps. This condition, colloquially termed leaky gut, allows undigested food particles and bacterial toxins to escape the digestive tract and enter the bloodstream. The immune system reacts by launching a chronic, low-grade inflammatory response. These circulating inflammatory cytokines can breach the blood-brain barrier, triggering neuroinflammation, which clinical studies have linked directly to the onset of major depressive disorders and chronic anxiety.

Stress Response and the HPA Axis

The gut microbiome plays a vital role in calibrating the Hypothalamic-Pituitary-Adrenal axis, which is the body’s primary stress response mechanism. A healthy, diverse microbiome acts as a natural brake on this system, helping the body downregulate cortisol production after a stressful event.

In contrast, an unhealthy microbiome leaves the Hypothalamic-Pituitary-Adrenal axis hyper-reactive. The brain perceives minor daily stressors as severe threats, flooding the system with cortisol and adrenaline. Over time, this chronic hormonal exposure alters brain architecture, diminishing emotional regulation and depleting the neural reserves necessary to resist psychological burnout.

The Gut’s Influence on Cognition, Focus, and Memory

The implications of the gut-brain axis extend far beyond emotional states; the health of the gastrointestinal ecosystem fundamentally dictates an individual’s ability to focus, process complex tasks, and retain memories.

Short-Chain Fatty Acids and Brain-Derived Neurotrophic Factor

When beneficial gut bacteria ferment dietary fiber, they produce metabolites known as short-chain fatty acids, including butyrate, propionate, and acetate. These fatty acids serve as essential signaling molecules that support cognitive function.

Butyrate, in particular, stimulates the production of Brain-Derived Neurotrophic Factor within the hippocampus. This specialized protein is responsible for neuroplasticity—the brain’s ability to grow new neurons, form new synaptic connections, and repair cellular damage. High levels of this protein correlate directly with enhanced memory retention, rapid learning capabilities, and a reduced risk of age-related cognitive decline.

Metabolic Toxicity and Brain Fog

Many individuals suffer from a persistent state of mental fatigue, low motivation, and poor focus, frequently described as brain fog. While often attributed to a lack of sleep or excessive screen time, the root cause is frequently found in the gut.

When digestion is compromised by a poor diet high in ultra-processed sugars and industrial seed oils, opportunistic yeast strains like Candida and pathogenic bacteria ferment sugars into metabolic byproducts such as acetaldehyde and ammonia. When these compounds absorb into the bloodstream and reach the brain, they act as mild neurotoxins, disrupting mitochondrial energy production within cerebral cells. The result is a noticeable drop in mental clarity, processing speed, and sustained attention span.

Optimizing the Axis for Mental and Cognitive Enhancement

Because the gut-brain axis is a bidirectional network, targeting gastrointestinal health represents a highly accessible, non-pharmacological strategy for improving mental well-being and unlocking cognitive potential.

  • Dietary Diversification: Consuming a wide variety of whole, fiber-rich plants provides the precise prebiotic substrates required to nourish diverse, beneficial bacterial species, directly increasing short-chain fatty acid synthesis.

  • Incorporation of Fermented Foods: Integrating traditional, unpasteurized fermented items like kefir, kimchi, and sauerkraut introduces live, active probiotic cultures that actively displace pathogenic strains and reinforce the intestinal barrier.

  • Stress Mitigation Practices: Because psychological stress can instantly alter gut motility and damage the microbiome, implementing daily mindfulness, deep diaphragmatic breathing, or targeted vagus nerve stimulation helps preserve digestive integrity and emotional balance.

Frequently Asked Questions

What is the distinction between prebiotics, probiotics, and psychobiotics regarding mental health?

Prebiotics are non-digestible dietary fibers found in whole foods that serve as fuel for beneficial gut bacteria. Probiotics are live, active microorganisms consumed through food or supplements that directly populate the gut ecosystem. Psychobiotics represent a specialized category of probiotics and prebiotics that, when ingested in adequate amounts, produce specific neuroactive substances that yield measurable, clinically validated benefits for psychological health and emotional regulation.

Can a severe course of antibiotics permanently alter an individual’s cognitive function?

A single, intense course of broad-spectrum antibiotics can decimate up to a third of the gut’s microbial diversity, leading to acute dysbiosis. Because the microbiome is heavily involved in synthesizing neurotransmitters and maintaining the blood-brain barrier, this sudden microbial depletion can trigger short-term cognitive side effects, including acute anxiety, depression, and significant brain fog. While the microbiome often recovers over several months, targeted dietary interventions are usually required to fully restore original cognitive vitality.

How does chronic sleep deprivation negatively impact the gut-brain axis?

The gut microbiome operates on its own internal circadian rhythm, which is highly sensitive to the sleep-wake cycles of the host. Chronic sleep deprivation elevates systemic cortisol levels, which increases intestinal permeability and alters gut motility. This disrupted environment inhibits the growth of beneficial, melatonin-producing bacterial strains, creating a negative feedback loop where poor sleep damages the gut, and a damaged gut further disrupts sleep architecture and cognitive recovery.

What role does the gut microbiome play in the development of neurodegenerative diseases like Alzheimer’s?

Emerging neurological research suggests that the early stages of neurodegenerative diseases like Alzheimer’s and Parkinson’s may actually originate in the gastrointestinal tract. Chronic gut dysbiosis leads to the accumulation of misfolded amyloid proteins and systemic inflammatory cytokines in the gut wall. These pathological agents can travel up the vagus nerve over many years, eventually entering the brain where they contribute to the formation of plaques, neuroinflammation, and progressive cognitive decline.

How quickly can a change in an individual’s daily diet alter their gut microbiome composition?

The gut microbiome is highly dynamic and responsive to environmental inputs. Clinical studies demonstrate that completely shifting from a highly processed diet to a whole-food, plant-based diet can alter the genetic profile and metabolic output of the gut microbiota in as little as 24 to 48 hours. However, while these initial microbial shifts occur rapidly, establishing a stable, resilient, and permanently altered bacterial ecosystem requires months of consistent dietary adherence.

Why does experiencing psychological nervousness or anxiety cause physical gastrointestinal distress?

This phenomenon occurs because of the bidirectional nature of the vagus nerve and the enteric nervous system. When the brain enters a state of acute stress or anxiety, it activates the sympathetic nervous system, initiating a fight-or-flight response. This survival mechanism diverts blood flow away from the digestive organs toward skeletal muscles, halts the secretion of digestive enzymes, and alters intestinal contractions. This sudden systemic shift causes immediate physical symptoms, including nausea, cramping, and acute changes in bowel motility.
read more
Finance

How Much Do MTF Interest Rates Cost?

When you use the Margin Trading Facility, brokers will charge you interest on the money they give you. This is called MTF interest rates. This interest is added every day to the amount you borrowed for your trade. It is usually shown as an annual percentage rate (APR), and most Indian dealers charge between 12% and 18%. The rate may change if:

The rules for the broker

The exact stock (stocks with higher volatility tend to have higher rates)
Your trade history or volume (some brokers offer better rates)
Conditions in the market (rates can go up during times of high risk)

When you use F&O margin calculator, you only pay the opportunity cost of blocking margin. With MTF, however, you pay clear interest because the broker is lending you money against your shares.

What Makes the F&O Margin Calculator Different from the MTF Context

Most of the time, F&O margin tools show:

SPAN plus the risk margin needed
Total margin that can’t be used for futures or options contracts
Possible gain or loss at different price levels

They pay attention to risk factors (like strike prices, lot sizes, and volatility) and upfront capital lock-in. In F&O, there is no ongoing interest cost because profits are refundable (less losses) and not seen as loans.

MTF, on the other hand, includes actual borrowing with interest added every day. When comparing tools, the F&O margin calculator helps with the efficient use of capital in futures, while MTF interest rate knowledge (through MTF calculators) is important for keeping costs low in the cash segment leverage.

Why it’s Important to Know About MTF Interest Rates

Realistic Analysis of Profitability
If you know the exact interest rate, you can figure out how much it really costs to keep a leveraged position. As an example:

A loan of ₹2 lakh at 15% p.a. equals ₹82 in interest every day.
It costs ₹4,920 in interest over 60 days.

You can figure out how much the price needs to rise in order to break even after interest is taken into account. This keeps people from making deals that look good on paper but can’t be done because of the cost of borrowing money.

Better Choices About Holding Periods

Interest changes quickly. Knowing the rate helps you set reasonable goals for time:

It’s cheap to borrow money and earn interest on short-term holds (days to weeks).
Medium holds (1–3 months): interest starts to show, but it’s still manageable, and the upside is high.
Long holds → interest adds up quickly and benefits often outweigh costs

This helps you get out of trades before interest drag wipes out gains or turns wins into positions where you break even or lose money.

As a filter, use interest rate awareness: only use MTF on trades where projected gains are much higher than the cost of borrowing. When used with F&O margin analysis, this two-tool method helps you wisely divide your resources—short-term conviction to F&O and medium-term conviction to MTF—so you can get the best results while minimizing risk.

read more
Casino

New tether casinos entering the market – Opportunities and risks

The stablecoin gambling sector continues attracting fresh operators launching platforms designed to capture market share from established competitors. new tether casinos arrive monthly with innovative features, aggressive promotions, and modern interfaces promising superior experiences. These emerging platforms present both enticing possibilities and genuine dangers that players must weigh carefully before committing funds to unproven operations.

Innovation versus stability tradeoff

Fresh entrants often incorporate cutting-edge technologies and design philosophies that veteran platforms lack. Modern payment integrations, social gaming elements, gamification systems, and mobile-first architectures represent areas where newcomers frequently surpass older casinos stuck with legacy infrastructure. These operators build their systems from scratch using current best practices rather than maintaining outdated frameworks requiring expensive overhauls. The innovation comes with inherent instability risks. Newly launched platforms haven’t endured stress tests that come from handling thousands of simultaneous users, processing large withdrawal volumes, or managing technical crises under pressure. Software bugs, server capacity issues, and payment processing failures surface more frequently during early operational phases before systems mature through real-world usage.

Promotional incentive advantages

Aggressive welcome offers:

  • First deposit bonuses reaching 200-300%
  • No-wagering free spin packages
  • Cashback programs with minimal restrictions
  • Loyalty points awarded at accelerated rates

Startups compete for attention through exceptional promotional value that established casinos rarely match. These platforms need to build player bases quickly, motivating generous incentives designed to overcome natural hesitation about untested operations. Smart gamblers extract substantial value during launch periods before promotions inevitably scale back once customer acquisition goals are met.

Liquidity and solvency concerns

The greatest danger with emerging platforms involves their financial backing and reserve management. New casinos may lack sufficient capital reserves to handle multiple large payouts simultaneously, creating situations where legitimate wins face payment delays or outright defaults. Without operational history demonstrating reliable withdrawal processing, players gamble twice on both games and the platform’s financial viability. Established competitors have proven their capacity to pay winners consistently over the years of operation. This track record provides confidence that new entrants cannot offer, regardless of ownership claims or capital assertions. Players trusting unproven platforms with substantial deposits accept risks extending beyond normal gambling probabilities.

Regulatory status evaluation

Newly launched casinos sometimes operate in jurisdictional gray areas while awaiting licensing approvals or deliberately avoiding regulatory oversight entirely. They may display “license pending” notices or vague claims about compliance without actual, verifiable credentials from recognised authorities. These ambiguous legal standing leaves players without recourse when disputes arise or platforms suddenly disappear. Operators who secure proper licensing before launching demonstrate commitment to legitimate long-term operations rather than quick profit extraction. Checking regulatory databases to verify license authenticity should precede any financial commitment to new platforms, regardless of attractive features or promotional offers.

Community feedback limitations

Players evaluating new casinos lack the extensive review histories available for established platforms. A three-month-old operation might have only dozens of user experiences documented online compared to thousands of reviews accumulated by veteran casinos. This limited data makes identifying patterns of good or problematic behavior extremely difficult. Early reviews may also reflect unusual circumstances not representative of long-term performance. Initial technical problems might get resolved quickly, or temporary generosity during launch periods could mask future restrictions. Waiting several months after launch allows more reliable information to accumulate before committing significant funds.

Technological architecture assessment

Modern platforms built on current frameworks often provide superior user experiences compared to older casinos, which are gradually updating legacy systems. Faster loading times, smoother mobile interfaces, better game integration, and more intuitive navigation reflect the advantages of recent development. These practical improvements genuinely enhance gambling enjoyment beyond superficial aesthetic changes. Untested code inevitably contains bugs and security vulnerabilities that only surface through extensive real-world usage. New platforms may suffer from account access issues, game loading failures, or payment processing errors that established competitors already identified and resolved years ago.

read more
Finance

How Overdraft Fees Shape Retail Banking Strategy

For decades, consumer retail banking operated on a relatively simple financial model. Financial institutions collected deposits from everyday consumers, paid a modest interest rate on those deposits, and loaned that pooled capital out to borrowers at a higher interest rate. The spread between the interest paid and the interest earned formed the core of bank profitability. However, as macroeconomic shifts, regulatory pressures, and changing consumer behaviors squeezed traditional interest margins, financial institutions had to diversify their revenue streams.

Non-interest income quickly transformed from a supplementary line item into a strategic necessity. Among the various components of non-interest income, none has been more historically significant, reliable, or intensely debated than the overdraft fee. The revenue generated when a consumer spends more money than is available in their checking account has grown to shape everything from product design to customer acquisition strategies. Analyzing the strategic role of overdraft fee revenue reveals the delicate balance retail banks must maintain between short-term financial performance, regulatory compliance, and consumer trust.

The Economics of Non-Interest Income in Retail Banking

To understand why overdraft revenue wields such immense strategic power, one must look at the structural costs of running a modern retail bank. Maintaining a vast network of physical branches, staffing those locations with trained personnel, deploying and servicing automated teller machines, and building secure digital banking applications requires massive, continuous capital expenditures.

Historically, banks offered free checking accounts as a loss leader to attract deposits. The assumption was that the institution could easily monetize those deposits through mortgages, auto loans, and commercial lending. However, during periods of prolonged low interest rates or economic volatility, the net interest margin shrinks. When lending becomes less profitable, the steady, predictable cash flow generated by account fees becomes the primary engine that funds daily operations and preserves shareholder value.

Overdraft fees represent a unique form of transactional revenue. Unlike a monthly maintenance fee, which consumers actively dislike and frequently seek to avoid by switching institutions, overdraft revenue is largely situational. It is triggered by specific consumer behaviors, allowing banks to market checking accounts as free while quietly relying on behavioral economics to generate substantial fee volumes behind the scenes.

Product Design and Customer Segmentation Strategies

The heavy reliance on overdraft revenue has fundamentally dictated how retail banks design their product suites and segment their target audiences. For years, the standard architecture of a basic checking account was optimized to facilitate, rather than prevent, occasional account shortfalls.

Transaction Processing Order

One of the clearest historical indicators of overdraft revenue shaping strategy was the implementation of specific debit processing sequences. Instead of processing transactions chronologically as they occurred throughout the day, many financial institutions utilized a high-to-low processing order. At the end of the business day, the bank’s systems would batch process the largest transactions first—such as a mortgage payment or rent check—before processing smaller debit card purchases like a morning coffee or a grocery run.

This system was strategically justified as a benefit to the customer, under the logic that ensuring vital, high-value payments cleared was of paramount importance. In practice, however, clearing the largest transaction first rapidly depleted the account balance. Consequently, subsequent smaller transactions each triggered an independent overdraft fee. This optimization turned a single instance of an overdrawn account into a compounding revenue event, netting the institution multiple fees in a single day from a single consumer.

The Profitability Profile of Low-Income Consumers

In traditional lending, low-income consumers with poor credit profiles are often viewed as liabilities or high-risk prospects. In the realm of retail banking fee structures, however, this demographic dynamic changes dramatically.

Data from financial regulators consistently reveals that a small percentage of chronic overdrafters accounts for the vast majority of overdraft fee revenue. These individuals are frequently living paycheck to paycheck, maintaining low average daily balances, and utilizing debit cards for frequent, low-dollar daily transactions. Strategically, this reality has created a complex paradox for retail banks. While high-net-worth individuals are highly prized for their investment and lending potential, the daily operational liquidity of many regional and community banks has historically been supported by the predictable fee generation of their lowest-income account holders.

Regulatory Headwinds and the Pivot to Fee-Free Models

The strategic reliance on overdraft revenue has faced unprecedented challenges due to aggressive regulatory intervention and shifting public sentiment. Agencies like the Consumer Financial Protection Bureau have placed overdraft practices under intense scrutiny, categorizing excessive, opaque fees as junk fees that unfairly penalize vulnerable consumers.

This regulatory pressure, combined with the rapid rise of digital-first neobanks and fintech startups, has forced traditional retail institutions to completely overhaul their strategic playbooks. Fintech challengers disrupted the market by offering accounts with zero overdraft fees, real-time balance alerts, and early paycheck access, creating a massive wave of customer attrition from traditional institutions.

To remain competitive and avoid looming regulatory caps, major national banks initiated a wave of voluntary reforms. Many institutions eliminated non-sufficient funds fees entirely, introduced 24-hour grace periods allowing customers to bring their accounts to a positive balance before a fee is assessed, and established low-cost, checkless accounts that physically prevent an account from going into the negative.

The Shift Toward Digital Monetization and Cross-Selling

As traditional overdraft fee revenue inevitably declines due to regulatory caps and market competition, retail banking strategy is shifting toward new methods of monetization. Financial institutions cannot simply absorb the loss of billions of dollars in annual fee revenue; instead, they are redesigning their businesses around digital engagement and predictive data analytics.

Interchangable Fee Optimization

With explicit consumer fees declining, banks are prioritizing volume-based revenue, specifically interchange fees. Every time a consumer swipes their debit card, the merchant pays a small percentage of the transaction to the issuing bank. By utilizing mobile banking applications to gamify spending, offering targeted cash-back rewards, and promoting contactless mobile payments, banks encourage consumers to use their cards more frequently for micro-transactions, replacing lost overdraft revenue with backend merchant fees.

Predictive Data and Ecosystem Cross-Selling

The ultimate survival of the retail banking segment relies on shifting from transactional monetization to relationship monetization. Modern retail banking strategies view the basic checking account not as a profit center through fees, but as a critical data ingestion point.

By analyzing a customer’s real-time deposit and spending patterns via machine learning algorithms, a bank can identify precise moments of financial need. If the system detects a user is consistently close to overdrawing, instead of charging a fee, the bank can automatically market a small-dollar, short-term line of credit with a transparent interest rate. Alternatively, if a user’s balance grows, the platform can seamlessly cross-sell high-margin products like automated investment services, wealth management, or insurance products. This strategic evolution transforms the bank from a passive collector of penalties into an active financial partner, preserving profitability while building long-term consumer loyalty.

Frequently Asked Questions

What is the mechanical difference between an overdraft fee and a non-sufficient funds fee?

An overdraft fee occurs when a financial institution chooses to cover a transaction despite the account lacking sufficient funds, allowing the payment to clear but driving the account balance into the negative. A non-sufficient funds fee, or NSF fee, is charged when the bank rejects the transaction entirely because of inadequate funds, bouncing the check or declining the transfer, meaning the payment is not made, and the consumer often faces an additional penalty from the merchant.

How does the opt-in rule from the 2010 Federal Reserve amendment alter how banks collect fees?

The 2010 regulatory amendment dictates that financial institutions cannot automatically enroll consumers in standard overdraft coverage for everyday debit card and ATM transactions. Consumers must explicitly opt-in to this coverage. If a customer does not opt-in, any debit card purchase or ATM withdrawal that exceeds their available balance will simply be declined at the point of sale, and the bank is legally prohibited from charging an overdraft fee for that specific transaction.

What are checkless or safe balance accounts, and why are banks introducing them?

Checkless accounts are specialized entry-level retail banking products specifically designed to eliminate the risk of overdrawing. These accounts do not offer physical paper checks and deactivate any backend credit extensions. Transactions are only approved if the digital balance can cover the exact amount in real time. Banks are introducing these accounts to comply with regulatory expectations for fair banking practices and to safely attract younger or unbanked demographics without exposing the institution to credit risk.

Do small community banks rely on overdraft revenue differently than large national institutions?

Yes, small community banks and credit unions typically exhibit a significantly higher strategic reliance on overdraft revenue than large national institutions. Major banks possess highly diversified revenue streams, including investment banking, wealth management, and massive commercial loan portfolios. Smaller institutions rely heavily on traditional consumer deposits and consumer fees, meaning regulatory reductions in overdraft fees place a disproportionate financial strain on the survival and operational budgets of local community banks.

How do fintech companies monetize accounts if they do not charge traditional overdraft fees?

Fintech companies and neobanks primarily monetize their user bases through interchange fee splitting, subscription models for premium account tiers, and partnership loops. When a user spends money using a fintech debit card, the company receives a portion of the merchant fee collected by the payment network. Additionally, many fintech platforms generate revenue by offering automated micro-loans, peer-to-peer transfer fees, or by cross-selling third-party financial products like insurance and high-yield savings accounts within their applications.

What is a grace period in modern overdraft policy, and how does it function?

A grace period is a strategic compromise implemented by many retail banks to soften the impact of overdraft penalties. When a customer executes a transaction that pushes their account balance below zero, the bank does not assess a fee immediately. Instead, the consumer is given a specified window of time, typically until the end of the next business day, to transfer funds or deposit cash to bring the balance back to zero or a positive standing, completely avoiding the penalty.

read more